Self-check 1 · Three statements
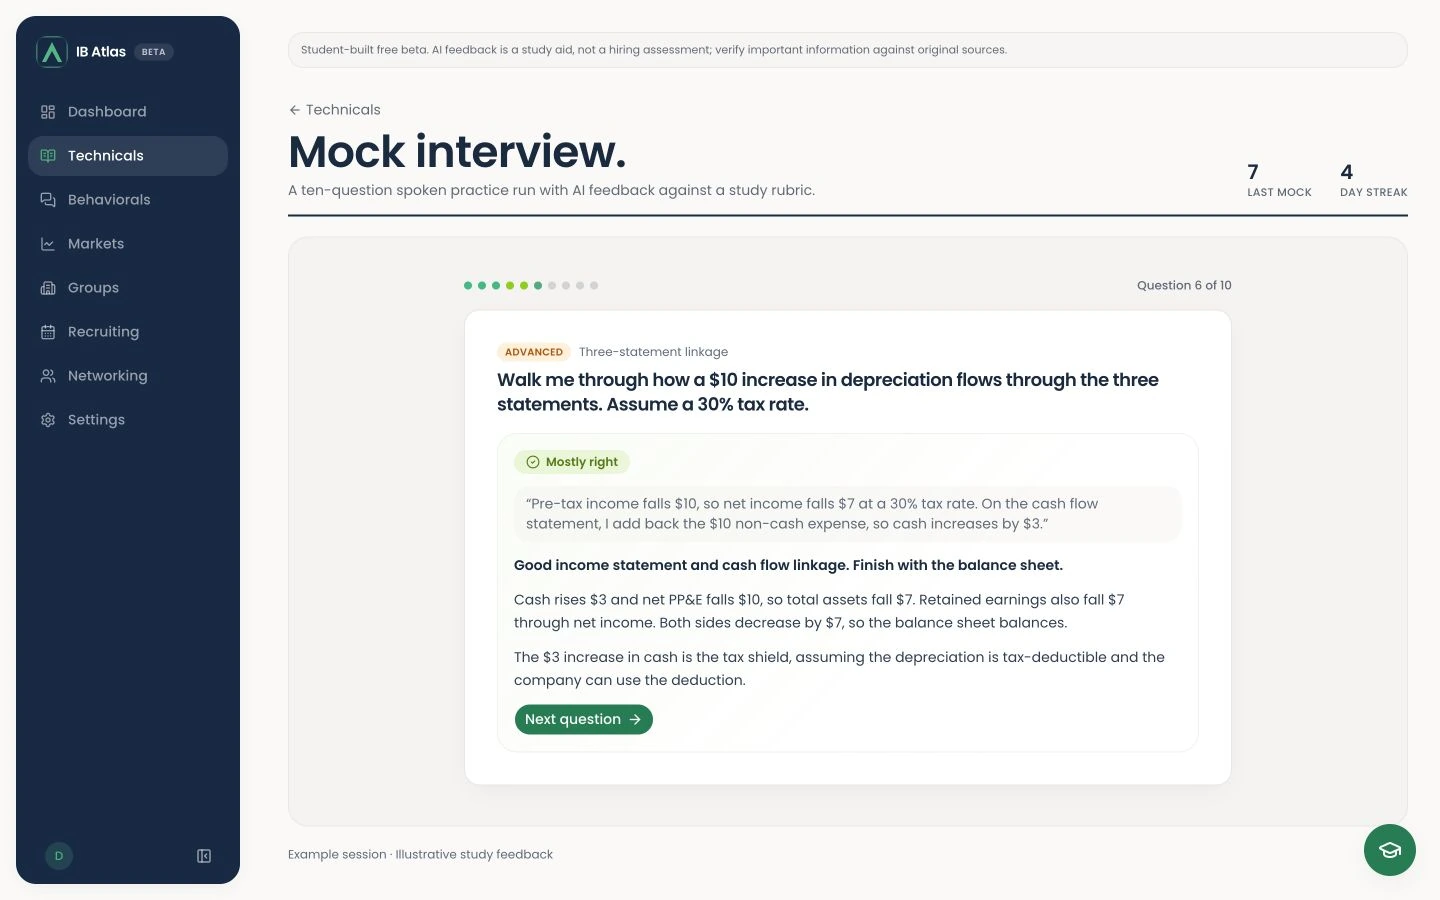
What does $10 of additional depreciation do?
Assume a 25% cash tax rate, an immediate tax benefit, no change in capital spending, and no other changes. Walk through the income statement, cash flow statement, and balance sheet.
Check the worked answer
- Pretax income falls by $10. Taxes fall by $2.50, so net income falls by $7.50.
- In cash from operations, start with net income down $7.50 and add back the full $10 non-cash depreciation expense. Cash rises by $2.50.
- On the balance sheet, net PP&E falls by $10 and cash rises by $2.50, so assets fall by $7.50. Retained earnings falls by the same $7.50 through lower net income.
Why: depreciation lowers accounting income but is added back in operating cash flow because it is non-cash. Under the stated tax assumption, the $2.50 cash-tax saving is the net cash effect.
Follow-up: What changes if the company cannot use the tax benefit immediately? The $2.50 cash increase should not be assumed; track the tax effect based on the facts given.